Explore potential car leasing costs with our Car Lease Calculator. Estimate monthly payments and test different interest rates, lease terms and residual (balloon) amounts to see how these variables may influence your repayments and overall leasing costs.
Calculator results are estimates based on the inputs and assumptions used and are provided for general information only. They are not quotes, offers, loan approvals, eligibility decisions or personalised recommendations. Actual costs and repayments may differ.
Car Lease Details:
Important!
Car Lease Interest Rates differ from lender to lender and will depend on your individual circumstances (credit history, employment status, age, etc.).
Car Lease Amortisation Calculator
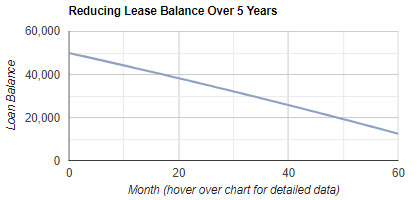
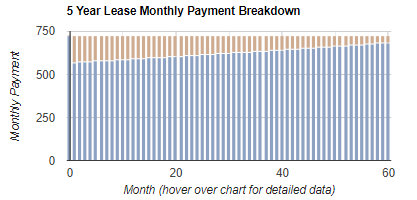
The following amortisation graphs detail month-by-month data on the progress of the proposed loan. The first chart below examines the reducing loan balance over the course of the finance contract term. The second graph illustrates the portion of each monthly repayment allocated to payment of interest vs principal reduction.
How to use our Vehicle Lease Repayment Calculator
Our Vehicle Lease Repayment Calculator helps you estimate monthly lease repayments for a motor vehicle by modelling three key variables: interest rate, lease term, and the residual or balloon amount payable at the end. It’s important because small changes to any of these inputs can materially affect cash flow, total interest over the term, and the end-of-lease obligation, helping you compare scenarios before you speak with a lender or novated leasing provider.
How to complete the form for the best result:
1. Purchase Price
Enter the total amount you want financed for the vehicle. Include relevant upfront costs you intend to roll into the lease (for example, on-road costs or insurance where applicable). Use whole numbers only (no decimals, commas, or dots).
2. Balloon or Residual Value (percent of purchase price)
Select the residual percentage. A higher residual generally reduces the monthly payment but increases the amount left owing at the end, which can increase overall cost across the term. Choose a residual that matches your intended end-of-lease plan (keep, refinance, or sell).
3. Term of Loan (years)
Choose the number of years. Longer terms usually reduce monthly repayments but can increase total interest paid. Select a term that suits how long you expect to keep the vehicle and your budget tolerance.
4. Interest Rate (per annum)
Select an interest rate to simulate. Use a conservative rate when stress-testing affordability, because your actual rate may differ depending on lender policy and your circumstances.
5. Calculate
Click calculate to generate your estimated monthly lease repayment and amortisation visuals.
How to interpret the results:
1. Monthly repayment estimate: Use this as a budgeting guide and compare scenarios by adjusting term, rate, and residual.
2. Amortisation charts: Review how the balance reduces over time and how much of each payment is interest versus principal; this highlights when interest costs are highest and the impact of a larger residual.
ASIC compliance note: This guide is general information only and does not consider your objectives, financial situation or needs. Consider the full lease contract, fees, taxes, insurance, maintenance, and end-of-lease options before deciding, and consider getting personal advice if needed.
Australia’s electric vehicle market has entered the final stretch of 2026 with another sign of sustained buyer interest, after the Electric Vehicle Council’s October vehicle sales report showed combined Tesla and Polestar battery electric deliveries of 4,168 vehicles for the month. The figure does not cover the whole EV market, but it is still useful for finance-minded buyers because it shows that demand for popular electric models remains active even as household budgets stay under pressure. - read more
Renault has reopened the Australian order book for the updated Megane E-Tech, giving EV buyers another mid-priced electric hatchback to consider as they plan finance for 2027 deliveries. The refreshed model is priced from $55,990 plus on-road costs in a single Esprit Alpine grade, with showroom arrivals due in the first half of 2027 after a break in local availability. - read more
Australia’s electric vehicle conversation is moving beyond the showroom. Recent energy and motoring coverage has put renewed attention on charging access, electricity tariffs and the real cost of keeping an EV on the road. For buyers planning an ev loan, that shift matters because affordability is no longer just about the purchase price, deposit and interest rate. - read more
Recent car loan market updates suggest competition in electric vehicle finance is still active, with some lenders using green loan offers and sharper advertised rates to attract borrowers. For Australian EV buyers, that is encouraging, but it also makes the comparison process more important rather than less. A lower headline rate can reduce borrowing costs, yet it is only one part of the overall loan decision. - read more
Australians buying an electric vehicle may be able to use a secured car loan, unsecured personal loan, novated lease or business vehicle finance. Each option works differently, with different ownership, security, tax, repayment and eligibility considerations. - read more
Understand the main factors that can affect EV loan rates, repayments and total borrowing costs in Australia, including comparison rates, fees, loan terms, deposits and balloon payments. - read more
In recent years, Australia has witnessed a significant shift towards eco-friendly transport solutions. Electric vehicles (EVs) are at the forefront of this movement, offering a sustainable alternative to traditional petrol and diesel cars. With advancements in technology and increased awareness about environmental impacts, more Australians are considering EVs as their next vehicle choice. - read more
EV rebates, stamp duty concessions, registration discounts and tax settings can change the upfront cost or cash flow of buying an electric vehicle. This guide explains how those rules may affect the amount you need to finance in Australia. - read more
Knowledgebase
Collateral: An asset that a borrower offers as a way for a lender to secure the loan.